What Is a Reasonable Service Charge for a Flat in England?
Could You Afford The Flat If The Roof Needed Replacing Next Year?
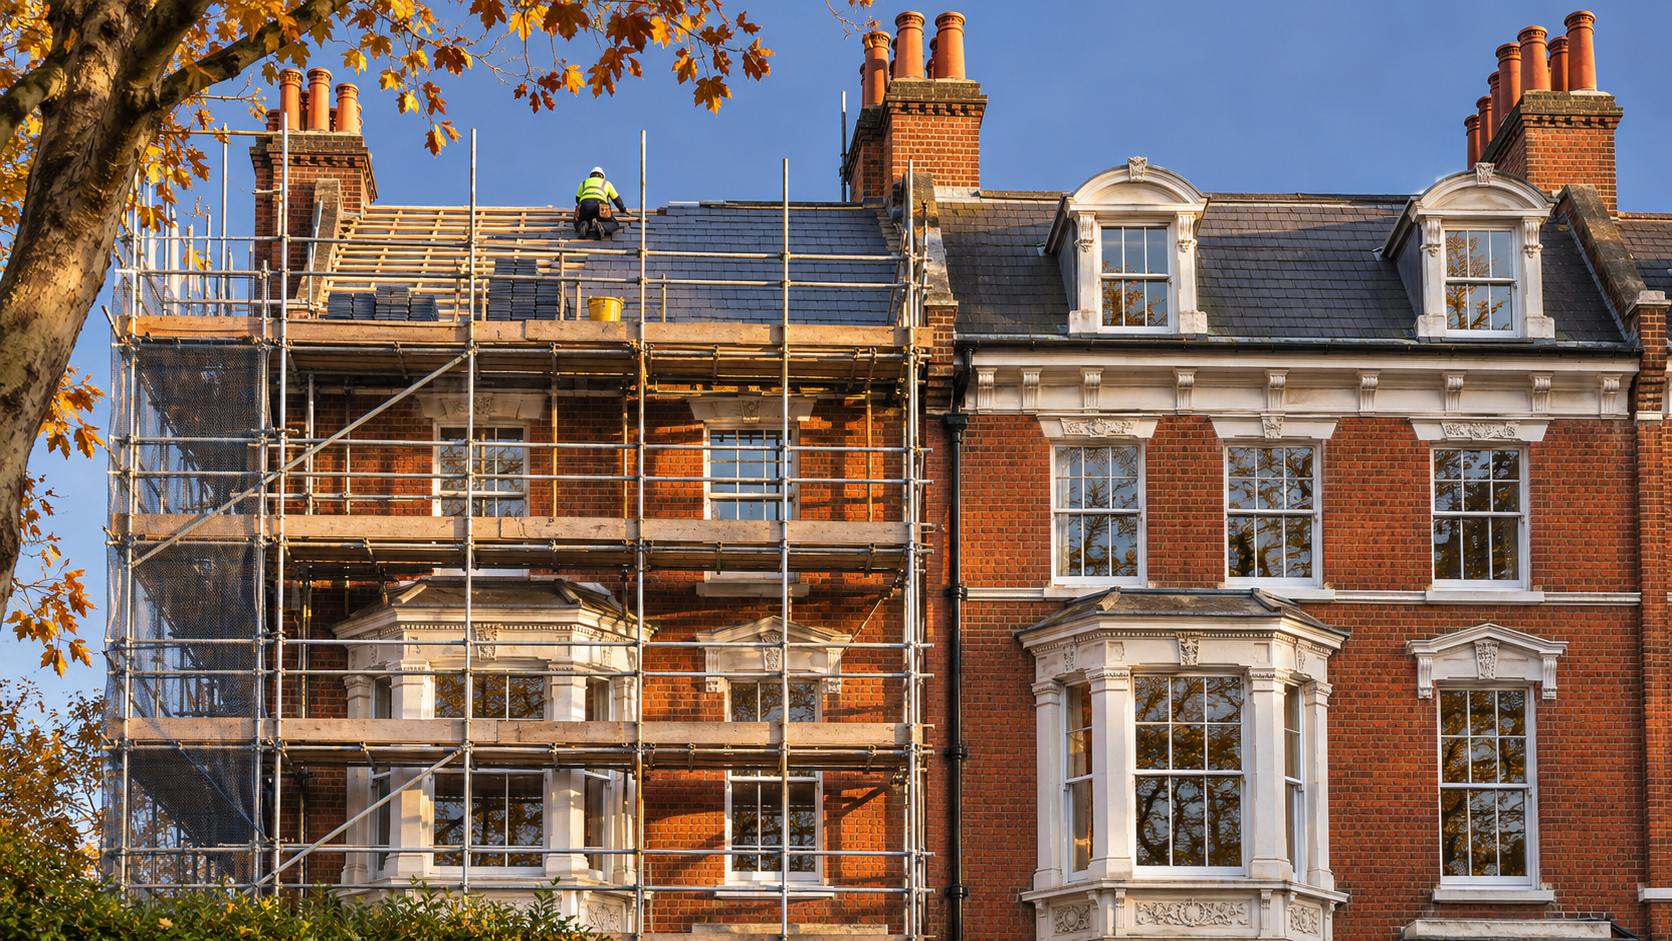
Imagine buying a flat with a service charge of £1,800 a year. You allow £150 a month on top of the mortgage. The figure fits your budget. Then the roof needs replacing, and your share of the bill, after the building’s savings have been used, is £4,000.
Both figures can be right. The £1,800 tells you what the building expects to collect from you this year. The £4,000 depends on what the roof costs, how much money is available for it and what proportion your lease requires you to pay. In this example, the detail that matters most at the viewing might be several floors above the flat you came to see.
For someone buying a leasehold flat in England, there are two affordability questions. What will it cost to live here in an ordinary year? How much cash might I need in an expensive one? The service charge accounts help answer the first. The lease, reserve fund and maintenance plan help answer the second.
What Does the Service Charge Actually Buy?
Start at the pavement and walk towards the flat. Someone may maintain the path, insure the building, clean the stairs, test the communal fire alarm and arrange repairs when the entrance door stops closing. A block with a lift also has machinery to inspect, service and eventually replace. These are among the costs a landlord or management company may recover through the service charge, where the lease allows it.
This makes two apparently similar flats difficult to compare on the listing alone. A £2,400 annual charge that includes communal heating, hot water and buildings insurance buys something different from a £1,700 charge where you pay for your own heating and hot water. The difference is £700 a year, or roughly £58 a month. Find out what the first flat includes before deciding which costs more to run.
The lease also determines how the bill is divided. Your flat might owe a fixed percentage of the block’s costs, with a different share for the wider estate. That distinction matters in a development with several buildings. If only one block needs a roof, dividing the quote by the number of homes across the entire development could give you a reassuring figure that has little to do with your bill.
Ground rent belongs on a separate line. It is a payment under the lease and buys no cleaning, insurance or repairs. Most new residential long leases granted in England from 30 June 2022 carry no financial ground rent. Buying an older lease today can still mean taking on its existing ground rent and review terms. Ask for the amount payable now, the next review date and the wording that determines any increase.
How Much Is a Typical Flat Service Charge in England?
The English Housing Survey offers a useful benchmark. In 2023–24, among owner-occupying leaseholders in flats who paid a service charge, the median annual charge was £1,500, equivalent to £125 a month. Half paid at or below that figure and half at or above it. The mean was higher, at £1,857.
Location made a difference. The median for flats was £1,865 in London and £1,300 across the rest of England. These are historical figures for what households reported paying. They can give a buyer a sense of scale. They cannot tell you whether the quote for insuring a particular converted mill is fair, or whether a small block charging £900 has saved enough for its next round of repairs.
A better comparison is with the same building over time. Ask for the last three years of accounts and the current budget. If the charge rose, look for the line that changed. A one-off drainage repair has a different implication for next year’s budget from a higher annual insurance premium. A rise in reserve contributions means some of the extra money is being put aside for future work. Those explanations point to different questions for the managing agent.
Why the Advertised Charge Can Change After You Move In
Most service charges are variable. In a building that collects them in advance, the managing agent draws up a budget before the invoices are all in. After the accounting year ends, actual spending is compared with what residents have paid.
Suppose your estimated share was £1,800, but your share of the final expenditure comes to £2,050. Depending on the lease, you could receive a balancing charge of £250. If spending comes in under budget, the lease governs what happens to the surplus. It might be credited against a future demand, refunded or transferred to a reserve.
There is a practical difference between the monthly cost and the payment date. An £1,800 charge averages £150 a month. If the lease requires two equal instalments, you need £900 when each one falls due. Before agreeing a completion date, ask your conveyancer for the amount you will need on completion and the date of the first demand you will pay directly. That avoids discovering that your carefully budgeted £150 is the first sixth of a bill due next week.
What Is a Reserve Fund, and Do You Get It Back?
A reserve fund, sometimes called a sinking fund, holds money for work that comes round less often than the annual bills. Exterior decoration, a replacement lift or a new roof are common examples. The landlord can collect reserve contributions only where the lease permits them. If your £1,800 charge already includes a £400 reserve contribution, your total is still £1,800. Adding the £400 again would count it twice.
You will usually leave your contributions behind when you sell. That can feel odd if you sell just before the scaffolding goes up. Consider the same arrangement from the buyer’s side. The buyer acquires a flat in a building where earlier owners have already paid towards a roof that wore out gradually during their ownership.
How much should the fund contain? A balance in isolation tells you surprisingly little. A £60,000 reserve could comfortably cover a £25,000 decorating programme. The same balance looks different if a £55,000 lift replacement comes first and the roof also needs attention. Ask how much is in the fund now, which jobs it may be used for, and how much of it is already committed. Then ask to see the maintenance plan that informed the annual contribution. The dates and estimates in that plan make the bank balance meaningful.
How a £120,000 Roof Becomes a £4,000 Bill
Take a hypothetical block of 20 flats. Each lease gives its owner an equal share of roof repairs. The estimated total cost is £120,000, including fees and VAT. The building has £40,000 available for the roof after accounting for other commitments.
Using that £40,000 leaves £80,000 to collect. Divided equally between 20 flats, the extra contribution is £4,000 each. If the reserve had been empty, each flat’s share would have been £6,000. If the full £120,000 had already been saved and could all be used for this job, the estimated work could be covered without a further roof bill.
Now put that alongside the household budget. Suppose the mortgage is £950 a month, the ordinary service charge is £1,800 a year and ground rent is zero. Together, the mortgage and ordinary service charge come to £1,100 a month, before council tax, utilities, contents insurance and repairs inside the flat. With the additional £4,000 roof bill, those first two costs and the roof together come to £17,200 in the works year, against £13,200 in an ordinary year.
Averaging the roof bill over 12 months makes it look like another £333 a month. The payment terms matter more than that average if the money is due in one instalment. Someone who can comfortably afford to live in the flat month by month may still struggle to meet a demand shortly after paying a deposit and moving costs.
What Does a Section 20 Notice Mean?
In England, a landlord generally has to consult leaseholders when qualifying works would cost any one leaseholder more than £250. The procedure takes its name from Section 20 of the Landlord and Tenant Act 1985. A separate threshold generally applies to a qualifying agreement lasting more than 12 months where any one leaseholder would pay more than £100 in an accounting year.
The £250 figure is easy to misread. It triggers consultation. A properly recoverable contribution can run to thousands of pounds. Consultation gives residents an opportunity to examine what is proposed and make observations. It does not give each flat owner a veto. The duty can apply even when there is enough money in the reserve to cover the work.
If a notice arrives, start with the reason for the job. Is water getting through because a local repair has failed, or has a survey found that the roof covering has reached the end of its life? Ask for the survey, the scope of work and, when available, the estimates. Check whether the quoted total includes scaffolding, professional fees and VAT. Those details make it easier to assess competing estimates and work out what the proposal means for your flat.
Where required consultation has not been carried out properly, recovery for qualifying works is generally limited to £250 per leaseholder unless the relevant legal requirements for an exception are met, including where the tribunal grants dispensation. If you dispute a demand, ask for the calculation and the lease clause behind it. The First-tier Tribunal in England can decide many disputes over whether a variable charge is payable or reasonable. Take advice before withholding payment, because leaving a demand unpaid can lead to enforcement.
Who Pays If the Bill Arrives After You Buy?
Imagine the seller hands over the keys in June. In September, the accounts for the previous year are finalised and a balancing demand arrives. All the work happened while someone else owned the flat. Can you simply forward the bill to the seller?
You may receive a valid demand for a period before you bought. What you owe under the lease and what the seller agreed to cover under the sale contract are separate questions. Your conveyancer can check for arrears before completion and negotiate how a later adjustment will be handled. One option is a retention, where an agreed sum is held back from the seller’s proceeds for a specified bill or period. Its value depends on the amount, what the agreement covers and when the money can be released.
A pending roof project poses a similar problem on a larger scale. “The seller will pay for the roof” sounds clear until the final cost exceeds the estimate, or the contract refers only to demands issued before completion. If the price you have offered depends on who bears that cost, have the arrangement recorded before exchange. Ask your conveyancer to explain what happens if the final figure or the billing date changes.
What to Ask Before Exchanging Contracts
The seller’s service charge statement, the lease and the management pack each answer a different question. The statement gives you a figure for the flat. The lease explains what can be charged. The management pack, including the leasehold property enquiries commonly called the LPE1, helps establish what the landlord or agent knows about the building. Read them together and ask for written answers to these questions.
What did this flat actually cost last year? Ask for the final charge, any balancing demand and the current estimate. Identify which household bills you still pay separately.
What percentage does this flat pay? Check the shares for the block, estate, lift and any other separate services. A ground-floor position alone does not establish who pays for the lift.
How much reserve money is available for the next major job? Get a dated balance and ask which projects already have a claim on it.
Which works are being discussed, surveyed or priced? Ask for the maintenance plan, relevant survey findings and consultation notices. A project can be under consideration before a formal notice exists.
What could fall due soon after completion? Ask about unpaid charges, unfinished accounts, payment dates and any agreement with the seller over pending bills.
What other costs follow from this particular lease? Check ground rent reviews, the remaining lease term, and fees for matters such as registering a purchase or seeking permission for alterations. A future lease extension belongs in a long-term budget of its own.
If the building has a known fire-safety or cladding issue, get specific advice on the building, the lease and any applicable statutory protections. The ordinary roof example assumes a repair recoverable under the lease. It is an unsuitable way to estimate an individual buyer’s liability for historic building-safety defects.
The most revealing question to ask at a viewing may be the simplest one. “When the next big job comes round, how much of it has this building already paid for?” An answer backed by a survey, a current reserve balance and the relevant paragraph of the lease gives you something a monthly service charge never could. It gives you a figure you can set against the savings you will actually have left after buying the flat.
Sources
English Housing Survey 2023–24 — Leasehold Experience gives the annual charges reported by flat owners in England, including the London comparison.
GOV.UK — Service Charges and Other Expenses explains ground rent, insurance, consultation thresholds and disputes.
Leasehold Advisory Service — Reserve or Sinking Funds explains how contributions are collected, used and treated when a flat is sold.
Leasehold Advisory Service — Common Problems and Disputes in Leasehold Transactions covers arrears, later demands and retentions when ownership changes.
Next Reads
Why Can a Budget Leak Move Mortgage Rates Before the Chancellor Speaks? follows a change in borrowing costs through to the fixed-rate deal a buyer sees.
UK Budget 2026 Explained: Who Wins, Who Loses And What It Means For Your Money examines the wider pressures on a household budget.
Who Pays for Britain’s £12 Billion Offshore Wind Farms, and When Could Households Benefit? explores how the cost of shared infrastructure can reach an electricity bill.
